


WHAT IS A CAR LOAN? LOW-INTEREST CAR LOAN TIPS 2026
Demand for car loans has increased significantly in recent years as cars are no longer used solely for transportation but have also become tools for business, investment and improving quality of life. However, to obtain bank approval for a loan with a suitable credit limit and interest rate, customers need to prepare transparent financial documents while also paying close attention to the appraisal of collateral. The article below explains the car loan process, key eligibility requirements and the important role of appraisal services when applying for bank financing.
What is a bank car loan?
A car loan is a form of financing in which a bank lends customers a substantial portion of the vehicle’s value, with repayment made in installments over an agreed term. Customers only need to prepare an initial amount of capital while the remaining amount is disbursed by the bank under the credit agreement.
Currently, many banks offer:
-
Loans of up to 70–85% of the vehicle’s value
-
Loan terms of up to 7–10 years
-
Financing for both new and used cars
This financial solution helps customers:
-
Reduce cash flow pressure
-
Acquire a vehicle sooner for work or business purposes
-
Optimize personal and business financial planning
Current car loan eligibility requirements
To qualify for a bank car loan, customers generally need to meet the following basic requirements:
Have a stable source of income
Banks assess repayment capacity based on:
-
Salary income
-
Business income
-
Company revenue
-
Rental income
-
Other legitimate sources of income
In general, monthly debt repayments should not exceed 50% of actual total income.
Have a good credit history
Customers with a poor credit history may face greater difficulty during the loan approval process, including:
-
Bad debt
-
Late payments
-
Excessive outstanding credit balances
Have suitable collateral
In addition to the vehicle being purchased, the bank may require supplementary collateral such as:
-
Real estate
-
Another car
-
Machinery and equipment
-
Business assets
The value of the collateral can directly affect:
-
Loan limit
-
Approval time
-
Interest rate policy
This is also why asset appraisal services are playing an increasingly important role in car loan applications.
What documents are required for a car loan?
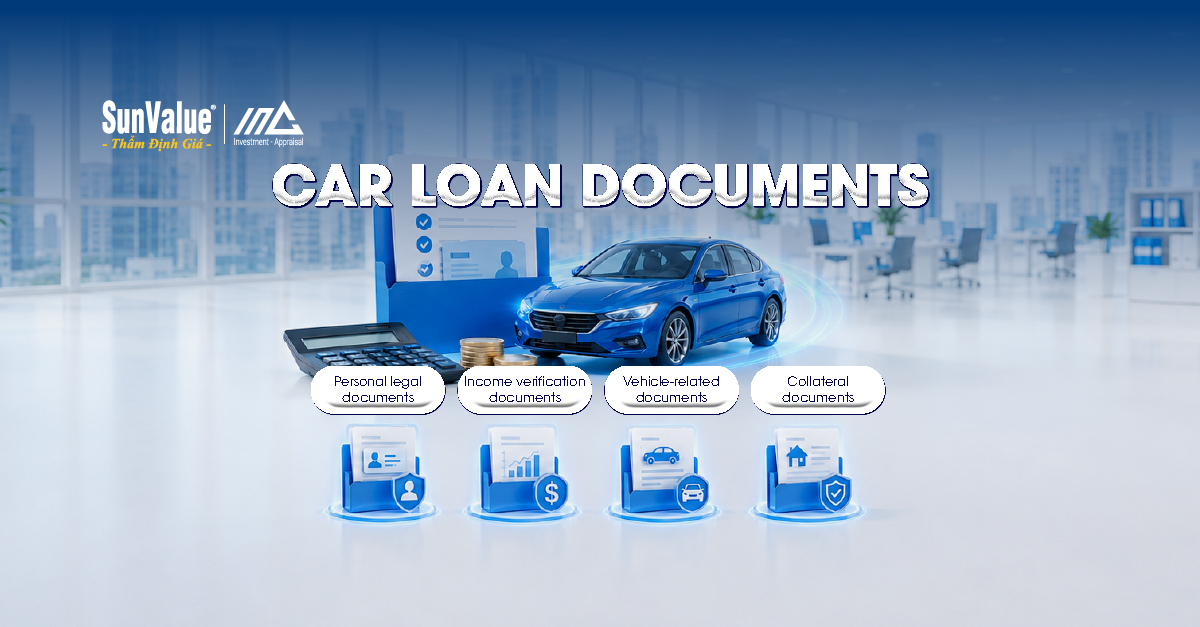
A basic car loan application usually includes:
Personal legal documents
-
Citizen ID card/ID card
-
Household registration book or proof of residence
-
Marriage certificate or certificate of single status
Income verification documents
-
Salary statements
-
Employment contract
-
Business license
-
Financial statements
-
Sales invoices or revenue records
Vehicle-related documents
-
Vehicle quotation
-
Purchase agreement
-
Showroom or dealership information
Collateral documents
If supplementary collateral is used, customers should prepare:
-
Certificate of ownership
-
Legal documents relating to the asset
-
Appraisal certificate, if available
Why does asset appraisal have a major impact on a car loan?
Many customers focus only on interest rates and overlook the valuation of collateral. In practice, this is one of the important factors affecting whether a car loan is approved.
The bank will assess:
-
The legal status of the asset
-
Market value
-
Liquidity
-
The appropriate loan-to-value ratio
If the asset is valued too low:
-
The loan limit may be reduced
-
The customer may need to contribute more of their own capital
-
Financial planning may become more difficult
Conversely, transparent asset documentation and a valuation that closely reflects market value can help:
-
Improve the likelihood of loan approval
-
Shorten application processing time
-
Optimize the bank loan limit
Asset appraisal solutions for a car loan
Today, many customers proactively use independent appraisal services before working with a bank in order to:
-
Determine the appropriate value of the asset
-
Support proof of financial capacity
-
Reduce the risk of undervaluation
-
Complete the loan application more efficiently
Indochina International Appraisal specializes in providing:
-
Moveable property appraisal
-
Car appraisal
-
Collateral appraisal for bank loans
-
Bank credit document consulting
With an experienced professional team and continuously updated market data, Indochina International Appraisal supports customers in determining asset values that closely reflect actual market conditions, comply with applicable regulations and meet the requirements of many banks.
Assets commonly appraised for a car loan
Depending on the loan application, banks may require appraisal of:
-
Townhouses
-
Apartments
-
Land plots
-
Cars already owned by the borrower
-
Machinery and equipment
-
Business assets
Among these, real estate remains one of the most commonly used forms of collateral because of its:
-
High value
-
Relatively stable value
-
Greater suitability for credit approval
Tips for getting a car loan approved quickly
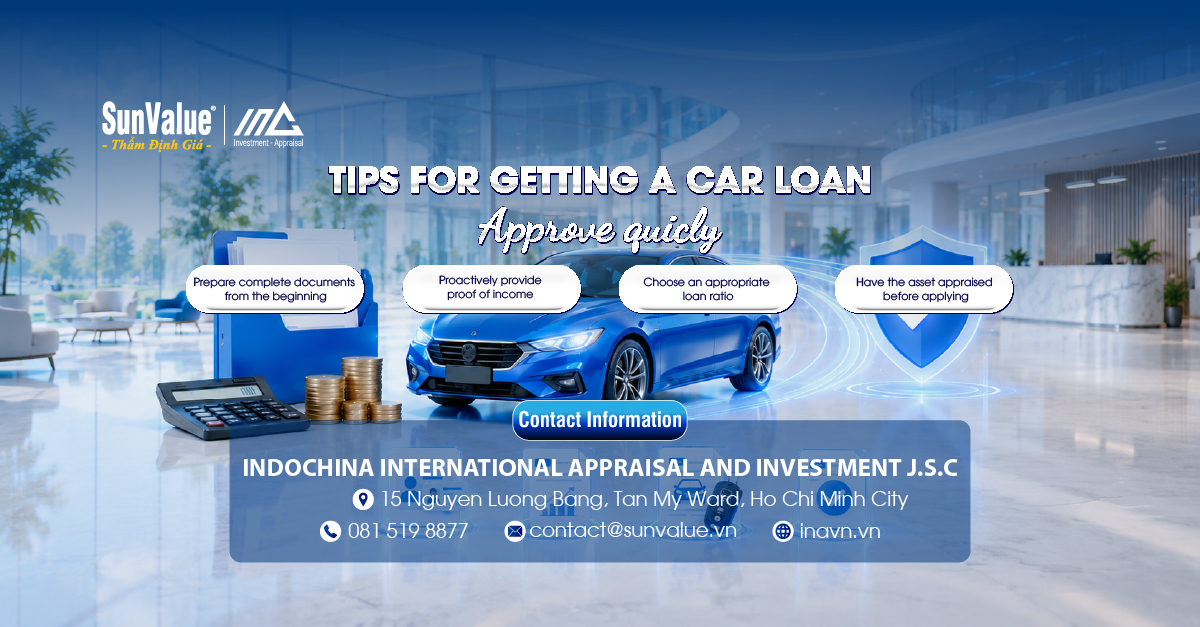
Prepare complete documents from the beginning
Clear and complete documents can help the bank:
-
Shorten the approval process
-
Minimize repeated requests for additional documents
-
Improve the credibility of the application
Proactively provide proof of income
For household businesses or companies, customers should:
-
Maintain transparent cash flow records
-
Prepare invoices and supporting documents
-
Have clear financial statements
Choose an appropriate loan ratio
Customers should avoid borrowing at an excessively high ratio if:
-
Income is unstable
-
Living expenses are high
-
There are several existing loans
Have the asset appraised before applying
This solution helps customers:
-
Understand the value of their assets in advance
-
Optimize the potential loan limit
-
Reduce the risk of the bank valuing the asset too low
Especially for large loans, having a professional appraisal certificate can improve the transparency of the application and provide the bank with a clearer basis for its assessment.
Should you take out a car loan in 2026?
As demand for transportation and business use continues to grow, a car loan remains a suitable financial solution for customers who:
-
Have a clear financial plan
-
Manage cash flow effectively
-
Choose an appropriate bank
-
Prepare transparent collateral documentation
In addition, using professional asset appraisal services can help customers:
-
Improve the likelihood of loan approval
-
Optimize the value of collateral
-
Reduce risks during the borrowing process
Do you need an asset appraisal for a car loan, additional documentation for a credit application or support in optimizing your bank loan limit? Contact Indochina International Appraisal for fast, accurate appraisal services that comply with applicable regulations and meet the requirements of many banks.
Indochina International Appraisal & Investment JSC (SunValue)
Hotline/Zalo: 081 519 8877
Email: contact@sunvalue.vn
Website: inavn.vn
Related article
REQUEST A QUOTE
Please share with us some of your information, we will contact you upon request