


Should you borrow when interest rates are high? Safe tips
Should you borrow when interest rates are high? This is a question that requires careful consideration from individuals, investors and businesses before deciding to take out a home loan, business loan or additional financing. As bank lending rates vary significantly, borrowers should not focus solely on interest rates but also understand their cash flow, repayment capacity and collateral value. At Indochina International Appraisal, we support clients through professional appraisal services, providing a clearer and more reliable basis for safer borrowing decisions.
How do high interest rates affect a loan?
Interest is the cost borrowers pay for using funds provided by a bank or credit institution. When interest rates rise, interest expenses also increase, placing greater pressure on personal income, business cash flow and long-term financial plans.
According to updates from Techcombank, bank lending rates in the market may currently range from approximately 5.5–24% per year, depending on the loan product, secured or unsecured lending method, bank and the borrower’s credit profile. Consumer loan rates may range from approximately 5–21% per year, with unsecured loans generally carrying higher interest rates than secured loans.
This shows that borrowers should not look only at the initially advertised interest rate. A loan that appears attractive during a promotional period may become a significant financial burden once it switches to a floating rate. For customers borrowing to purchase a house or land, renovate a home or obtain a mortgage, an increase of just 1–2% per year can materially affect total financing costs.
For businesses, high interest rates increase the cost of capital, directly affecting profitability, cash flow management and expansion plans. Businesses borrowing to invest in projects, purchase machinery and equipment, supplement working capital or restructure their finances need to assess the efficiency of capital use carefully before making a decision.
Should you borrow when interest rates are high?
The answer is: you can still borrow, but the decision should not be based on emotion.
High interest rates do not mean that every loan is a poor financial decision. In many situations, borrowing may still be necessary if the loan serves a genuine need, has the potential to generate value and the borrower has a clear repayment plan.
Borrowers may consider taking out a loan if:
-
The loan serves an essential need such as purchasing a home, renovating a property or supplementing business capital.
-
The borrower has stable income or cash flow.
-
The borrower has sufficient equity and is not entirely dependent on borrowed capital.
-
The collateral has a clearly established value and transparent legal status.
-
Monthly repayments remain within a manageable level.
-
The borrower has already considered scenarios in which interest rates rise after the promotional period.
Conversely, borrowers should exercise caution if:
-
The loan is used for short-term speculation.
-
The loan amount is too high relative to financial capacity.
-
The borrower does not clearly understand the interest rate after the promotional period.
-
There is no emergency fund.
-
The collateral value has not been properly determined.
-
The borrower relies entirely on expectations of asset price appreciation.
In 2026, the State Bank of Vietnam has set an overall credit growth orientation of approximately 15%, subject to adjustments based on actual developments. This indicates that credit continues to support the economy, but borrowers still need to clearly demonstrate the purpose of the loan, financial capacity and collateral.
Therefore, the key question is not simply “should you borrow?”, but rather “is this loan truly safe based on your current cash flow and asset value?”
When should you still borrow despite high interest rates?
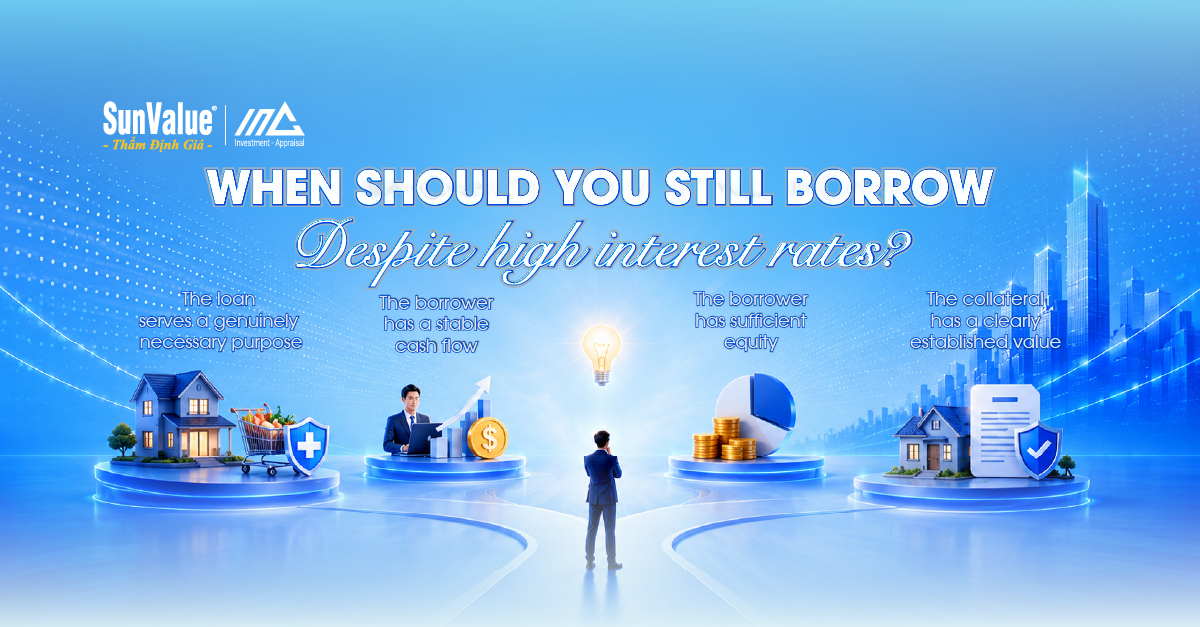
Borrowers may consider taking out a loan during a period of high interest rates if the following conditions are met:
1. The loan serves a genuinely necessary purpose
Borrowing may be appropriate when the loan is used for practical needs such as:
-
Purchasing a home for residential purposes.
-
Repairing or renovating a home.
-
Supplementing capital for production and business operations.
-
Purchasing machinery and equipment for business operations.
-
Investing in projects with clear cash flow.
-
Financial restructuring to stabilize operations.
For homebuyers, property is not only a form of wealth accumulation but also serves a genuine housing need. For businesses, a loan can help maintain operations, expand production or take advantage of timely business opportunities.
2. The borrower has stable cash flow
Cash flow is a key factor in determining repayment capacity. Whether interest rates are high or low, borrowers need to ensure that debt repayments remain within their financial capacity.
Before borrowing, customers should assess:
-
Is monthly income stable?
-
Is business cash flow consistent?
-
Is there an emergency reserve if income declines?
-
Can repayments still be made if interest rates increase by another 1–2%?
-
Would the loan place excessive pressure on living expenses or business operating costs?
Answering these questions helps borrowers take greater control of financial risks.
3. The borrower has sufficient equity
When interest rates are high, borrowers should avoid relying entirely on bank financing. The greater the amount of equity available, the lower the pressure from interest expenses.
Having sufficient equity can help customers:
-
Reduce the amount that needs to be borrowed.
-
Reduce total interest expenses.
-
Improve the likelihood that the bank will consider the application.
-
Remain more financially flexible during market fluctuations.
-
Reduce the risk of cash flow imbalance.
For real estate transactions, customers should consider a loan-to-value ratio appropriate to the property value. For businesses, equity reflects financial capacity and the investor’s commitment to the business plan.
4. The collateral has a clearly established value
For secured loans, collateral plays an important role in determining the loan limit. The clearer the legal status, the more stable the value and the stronger the liquidity of the asset, the stronger the basis for the bank to assess the loan application.
Suitable collateral generally needs to meet the following conditions:
-
Clear legal status.
-
Appropriate market value.
-
Good liquidity.
-
No disputes or legal complications.
-
Suitability for the borrowing purpose.
-
An independent appraisal basis.
This is why asset appraisal before obtaining a bank loan becomes particularly important during periods of fluctuating interest rates.
When should you not borrow when interest rates are high?
Not every loan should be taken out. During periods of high interest rates, borrowers should exercise particular caution in the following situations:
1. Borrowing for short-term speculation
Borrowing is generally not advisable when the decision relies mainly on expectations that an asset will rapidly appreciate in value. If the market does not perform as expected, borrowers may face multiple pressures:
-
High interest expenses.
-
Difficulty selling the asset to recover capital.
-
Risk of cash flow imbalance.
-
Reduced liquidity of the asset.
2. Income or cash flow is unstable
Individuals with highly volatile income or businesses with unstable cash flow should carefully consider whether to borrow.
Warning signs include:
-
Income depends on a single source.
-
Business revenue is inconsistent.
-
There is no emergency fund.
-
Living or operating expenses are increasing.
-
Debt repayments account for an excessive proportion of income.
3. The post-promotional interest rate is unclear
Many loan packages offer low interest rates during the initial period before switching to floating rates. If borrowers focus only on the initial rate, they may underestimate the actual total cost of borrowing.
Before signing a loan agreement, customers should clarify:
-
How long does the promotional interest rate apply?
-
How is the interest rate calculated after the promotional period?
-
What is the additional interest margin?
-
Is there an early repayment fee?
-
Is repayment calculated on a declining balance or through equal installments?
-
How will repayments change if market interest rates rise?
4. The asset value has not been properly determined
For secured loans, if the collateral value has not been properly determined, customers may have unrealistic expectations regarding the loan limit.
Common risks include:
-
The actual asset value is lower than expected.
-
The bank approves a lower loan limit than anticipated.
-
The buyer purchases an asset above its actual value.
-
The asset has legal or liquidity issues.
-
The borrowing plan is affected because there is no reliable valuation basis.
How much should you borrow safely when interest rates are high?
There is no single figure that is suitable for everyone. However, a safe loan amount should be calculated based on income, cash flow, expenses, collateral value and the borrower’s ability to maintain a financial buffer.
For individual customers, the following should be calculated in advance:
-
Monthly net income.
-
Fixed living expenses.
-
Family expenses, tuition fees, healthcare and insurance.
-
Emergency reserves.
-
The maximum affordable debt repayment.
-
Repayment capacity if interest rates increase.
For businesses, the following should be considered:
-
Business cash flow.
-
Capital turnover.
-
Profit margins.
-
Payback period.
-
Financing costs.
-
Efficiency of borrowed capital.
-
Collateral value.
For example, if a customer borrows VND 2 billion, an increase of just 1% per year in the interest rate could increase annual interest expenses calculated on the initial outstanding balance by approximately VND 20 million per year. For large loans such as home loans, project investment loans or working capital loans, this increase can directly affect monthly cash flow.
Before borrowing, customers should prepare at least three scenarios:
-
Scenario 1: Interest rates remain unchanged.
-
Scenario 2: Interest rates increase by 1–2% per year.
-
Scenario 3: The post-promotional interest rate is higher than expected.
Preparing these scenarios in advance helps borrowers determine whether the loan would remain financially manageable if market conditions change.
Why should assets be appraised before obtaining a bank loan?
Asset appraisal is an important step that helps customers understand the actual value of an asset before using it as collateral. It also provides a basis for working with banks, partners, investors or other relevant parties.
For individual customers, appraisal helps:
-
Determine the value of real estate, houses, land and apartments.
-
Estimate a suitable loan limit.
-
Avoid purchasing an asset above its actual value.
-
Assess the liquidity of the asset.
-
Be better prepared when working with banks.
For businesses, appraisal supports:
-
Real estate appraisal for borrowing purposes.
-
Appraisal of machinery, equipment and production lines.
-
Appraisal of vehicles and movable assets.
-
Appraisal of businesses, shares and intangible assets.
-
Investment project appraisal.
-
Asset appraisal for debt resolution, capital contribution, transfers or financial restructuring.
In practice, many customers focus primarily on whether a bank will approve a loan without fully assessing the actual value of the collateral, its liquidity or whether it is suitable for the intended borrowing purpose. Independent appraisal helps customers reduce the risk of unrealistic expectations regarding the loan limit while providing an additional basis for developing an appropriate financial plan.
How does Indochina International Appraisal help customers borrow more safely?
As interest rates and credit conditions fluctuate, Indochina International Appraisal not only provides appraisal results but also gives customers an additional asset data basis for making safer borrowing decisions.
Indochina International Appraisal appraises a wide range of assets for borrowing and financial management purposes, including:
-
Real estate, houses, land, apartments, buildings and projects.
-
Machinery, equipment and production lines.
-
Vehicles.
-
Businesses, shares and intangible assets.
-
Investment projects.
-
Collateral for bank loan applications.
-
Assets for debt resolution, purchase, sale, transfer, capital contribution or financial restructuring.
The value of an appraisal report lies not only in the final figure but also in the methodology, data and analytical process behind it. Indochina International Appraisal focuses on:
-
Conducting physical inspections of assets.
-
Collecting and reviewing legal documentation.
-
Analyzing asset characteristics.
-
Cross-checking market data.
-
Selecting appropriate appraisal methods.
-
Providing guidance on appraisal results according to the intended purpose of the report.
With experience handling a wide range of appraisal assignments, Indochina International Appraisal understands that each customer has different objectives. Therefore, we not only provide appraisal results but also help customers understand asset values and how appraisal results can be used in specific circumstances.
What needs are our appraisal services suitable for?
Indochina International Appraisal supports customers with a wide range of practical needs, including:
-
Real estate appraisal for bank loans.
-
Collateral appraisal.
-
Appraisal of machinery, equipment and vehicles.
-
Appraisal of businesses, shares and investment projects.
-
Asset appraisal for debt resolution.
-
Asset appraisal for purchase, sale, transfer or capital contribution.
-
Asset appraisal for financial restructuring.
-
Asset value consulting before borrowing, investing or entering into a transaction.
With professional expertise as our foundation and customer value at the center of our approach, Indochina International Appraisal aims to be a trusted partner for individuals, businesses and organizations in appraising, managing and maximizing asset value.
Conclusion
High interest rates do not mean that borrowing should always be avoided, but borrowers need to exercise greater caution before making a decision. A safe loan should be based on actual cash flow, a clear purpose for using the funds and an accurately determined collateral value.
Before obtaining a bank loan, customers should proactively arrange an asset appraisal as a basis for determining an appropriate loan limit, managing risks and developing a suitable financial plan. Contact Indochina International Appraisal for consultation on the appraisal of real estate, collateral, machinery and equipment, businesses and investment projects before borrowing.
Indochina International Appraisal & Investment JSC (SunValue)
Hotline/Zalo: 081 519 8877
Email: contact@sunvalue.vn
Website: inavn.vn
Related article
REQUEST A QUOTE
Please share with us some of your information, we will contact you upon request